Options volumes on NSE, BSE decline over 50% during FY26 after SEBI crackdown
7th August, 2026
Indian exchanges saw 62.8 billion index options contracts traded in the FY 2025-26, compared to 131.4 billion lots during the previous financial year, due to measures taken by the regulator to curb excessive retail speculation in equity derivatives.
The Securities and Exchange Board of India (SEBI) on Thursday published its annual report for the FY 2025-2026 which showed 52% decline in index options traded across the National Stock Exchange (NSE) and the Bombay Stock Exchange (BSE).
“This significant decline in derivatives volumes during 2025-26 was possibly driven by a series of regulatory interventions including increased contract sizes, the rationalisation of weekly expiries, mandatory upfront premium collection, alongside an increase in the securities transaction tax,” the SEBI report read.
Policy developments initiated by the Indian regulator in FY 2025-26 include formulation of Future Equivalent Open Interest for better measurement of risk in equity derivatives; framework for intraday position limits monitoring; introduction of pre-open session and additional eligibility criteria to introduce derivatives on non-benchmark indices.
However, the combined notional turnover in the equity derivatives segment across NSE and BSE went up by 4.3 per cent to ₹110.4 quadrillion (£862.86 trillion) during the financial year ending March 2026, compared to ₹106 quadrillion in FY2024-25.
The watchdog said the India Volatility Index (VIX), calculated by the NSE to measure the market's expectation of volatility over the next 30 calendar days, increased by 60.7 per cent, climbing from 12.7 to 20.4 index points between March 31, 2025 and April 8, 2025.
SEBI said the spike in India VIX mirrored Cboe VIX, which also rose 134.9 per cent during the same six-day trading period. The India VIX stabilised and maintained a yearly average of 13.7 points in the FY 2025-26, following the initial spike. In March 2026, the index went up by 103.6 per cent triggered by the US-Iran conflict (see chart 1).
Chart 1
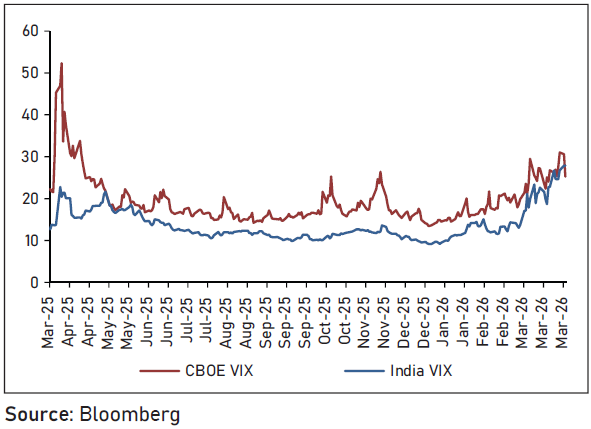
Source: SEBI/Bloomberg
NSE recorded 3.2 billion contracts traded last month across index and single stock derivatives, up 11.85% year-on-year, driven by strong momentum in stock options.
The Indian exchange group is exploring a new volatility index with a different in-house computation methodology compared to the existing India VIX, according to a Business Standard report last month.
Related topics
Related Articles
All Insights21st September, 2026
FutureSports strikes MLB deal ahead of planned CME baseball futures
FutureSports has agreed a deal with Major League Baseball (MLB) to create performance indexes for all 30 MLB teams, paving the way for CME Group to list cash-settled futures linked to the benchmarks, pending regulatory review.
Zak Jakubowski
21st September, 2026
EBA issues new risk management rules for third-party services
The European Banking Authority (EBA) has published its final guidelines on the management of third-party risk regarding non-ICT services, as it looks to strengthen operational resilience and regulatory compliance across the EU financial sector.
Aravind Bulusu
21st September, 2026
ECB to invest own funds in tokenised securities using Pontes
The European Central Bank (ECB) is preparing to invest part of its own funds in tokenised securities and settle the transactions in central bank money through the Eurosystem's newly launched Pontes platform.
Zak Jakubowski
