Kalshi sees institutions combining event contracts with traditional derivatives
1st October, 2026
Institutional investors are increasingly using prediction markets to isolate event-driven risks and generate signals for traditional derivatives markets, according to Kalshi's head of institutional.
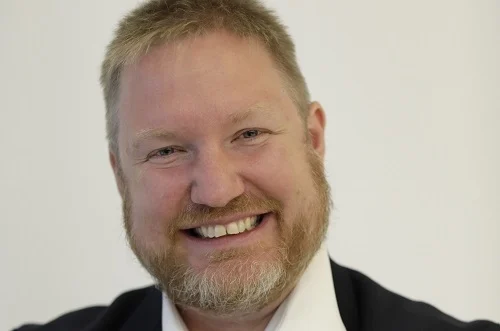
Andy Ross, head of institutional at Kalshi (pictured), told FOW on Monday that firms are using both event contracts and their underlying data as the US prediction market operator expands its institutional trading and risk-management offering.
“It’s both. The data itself is valuable because you’re getting a market price around a real-world event, and we’re seeing institutions use those probabilities as signals,” Ross told FOW in an interview. “At the same time we’re seeing them trade the contracts when they want to isolate and hedge the actual event driving their exposure.”
The comments follow BMLL's integration of Kalshi's historical prediction-market data into its institutional dataset earlier this month, which allows quantitative and systematic firms to compare Kalshi data with traditional markets and backtest strategies around macroeconomic events.
Kalshi targets specific event risk
Ross said legislative and policy risk is one area where institutions are using event contracts to isolate risks that may otherwise be managed indirectly through conventional derivatives.
“Around the CLARITY Act, we had people trading millions of dollars and doing block-size trades,” he said. “You could hedge the Bitcoin exposure with futures or options, but what was actually driving the risk at that moment was whether the legislation passed. So you can isolate that specific risk rather than relying on the underlying asset to move the way you expect.”
Kalshi's approach is to develop contracts around specific risks rather than concentrating liquidity in a small number of highly liquid proxies and leaving clients to manage the resulting basis risk.
“Kalshi is unlike any other exchange in that we want to know what the underlying risk is - we are not trying to bring liquidity into one or two super liquid proxies where the client manages the basis risk but generate specific risk products to hedge that risk,” Ross said. “We don’t just have the liquidity in the products, but can generate pricing and liquidity in new markets for exactly the risk you have to hedge.”
Ross said this forms a key part of Kalshi's institutional strategy as it looks to compete with established methods of transferring specific risks.
“This is a key strategic part of the institutional development challenging reinsurance markets and otc swap transactions with a centrally cleared, and continuously priced product,” he said.
Event markets provide cross-market signals
Differences between prediction-market prices and conventional derivatives could provide useful information to institutional traders.
“The markets don’t always give you the same answer,” he said. “BMLL has looked at Kalshi and Fed funds futures across 11 FOMC meetings and found measurable differences in how they priced the expected outcome. That divergence can itself be useful information.
“I’d be cautious about generalizing that across SOFR, FX and equities yet, but that’s exactly the kind of cross-market research this data makes possible.”
Standardising prediction-market data alongside traditional market datasets also allows institutions to conduct relative-value analysis and backtest strategies, while firms are examining event probabilities as inputs into systematic trading models.
“We know firms are looking at these probabilities as trading signals and potential sources of alpha, but I’d be careful about saying how many have already put fully systematic strategies into production,” Ross said. “Macro and rates are an obvious starting point because events like Fed decisions, CPI and payrolls feed directly into traditional markets. Commodities and equities are also natural areas where an event probability can become another input into an existing model.”
Kalshi builds institutional liquidity
Kalshi is bringing more brokers, clearing firms and liquidity providers into its ecosystem as it seeks to increase institutional participation, according to Ross.
“We’re also continuing to bring more brokers, clearing firms and liquidity providers into the ecosystem. Depth still varies by market, so there’s more work to do, but the institutional infrastructure around the liquidity is much stronger and continuing to grow.”
Ross said capital efficiency, connectivity, clearing and compliance are among the remaining barriers to integrating event contracts into traditional derivatives workflows.
“Fully funding every position is capital-intensive, so introducing leverage on appropriate event contracts, subject to CFTC approval, would make the capital treatment more familiar to traditional derivatives firms. But leverage by itself doesn’t solve liquidity or infrastructure, as you have to build all of those pieces together.”
Kalshi plans to offer leverage on some event contracts, excluding sports markets, subject to regulatory approval.
“Leverage matters in capital efficient markets and for institutional investors we will be offering some contracts with leverage - not sports - on a purpose built, conservative and risk managed leverage model.”
Multivariate events and perpetual futures
Kalshi is also looking to Multivariate Events and perpetual futures as it expands the products available alongside traditional derivatives.
“Multivariate Event expand the ways institutions can manage risk alongside traditional futures and options. They let firms tailor exposure around combinations of outcomes, while perpetual futures provide continuous exposure without an expiry,” Ross said.
“The big opportunity here is to bring innovations like these onshore and into a regulated market, with leverage being a critical part of making them viable at institutional scale.”
Ross added: “Capital efficiency is essential if these markets are going to grow meaningfully, and when done within an onshore regulated framework, that gives institutions more powerful tools to manage risk. And, ultimately, makes markets stronger.”
This comes as BMLL chief executive Paul Humphrey told FOW this week that prediction-market data should increasingly be treated as an asset class in its own right, with the data provider planning to add more prediction-market venues as institutional demand grows.
Related topics
Related Articles
All Insights7th October, 2026
TS Imagine adds regulatory intelligence to TSIQ AI platform
TS Imagine has integrated Gentek.ai’s regulatory intelligence technology into its TSIQ artificial intelligence platform, allowing capital markets firms to use natural-language queries to identify regulatory reporting requirements and potential data gaps.
Zak Jakubowski
7th October, 2026
Securitize, LG CNS partner to advance South Korea’s digital asset ecosystem
The blockchain company has struck a deal with South Korean artificial intelligence and IT services firm LG CNS to explore tokenised funds, equities, stablecoins and digital asset infrastructure for Korean financial institutions.
Aravind Bulusu
7th October, 2026
HKEX derivatives volumes slump 18.9% as index trading slows
The Asian exchange recorded average daily futures and options volume of 1.48 million lots in September, extending the slowdown from August as trading in key equity-index products weakened.
Narayani Srinivasan