CFTC approves Rothera’s Tesla KPI event contract as Selig points to closer SEC coordination
28th October, 2026
The US derivatives regulator classified the contract on Tesla’s quarterly earnings as a swap under the Commodity Exchange Act (CEA), while signalling a harmonised approach with competing listings overseen by the Securities and Exchange Commission (SEC).
The Commodity Futures Trading Commission (CFTC) on Tuesday approved Rothera Exchange and Clearing’s contract on whether Tesla reports fourth-quarter 2026 adjusted earnings per share above $0.65 (£0.49), classifying the product as a swap under the CEA.
The agency approved the cash-settled, binary contract for listing on Rothera, as a designated contract market (DCM), and for clearing as a swap.
This comes two weeks after the SEC approved Cboe Global Market’s request regarding its corporate key performance indicator (KPI) contracts.
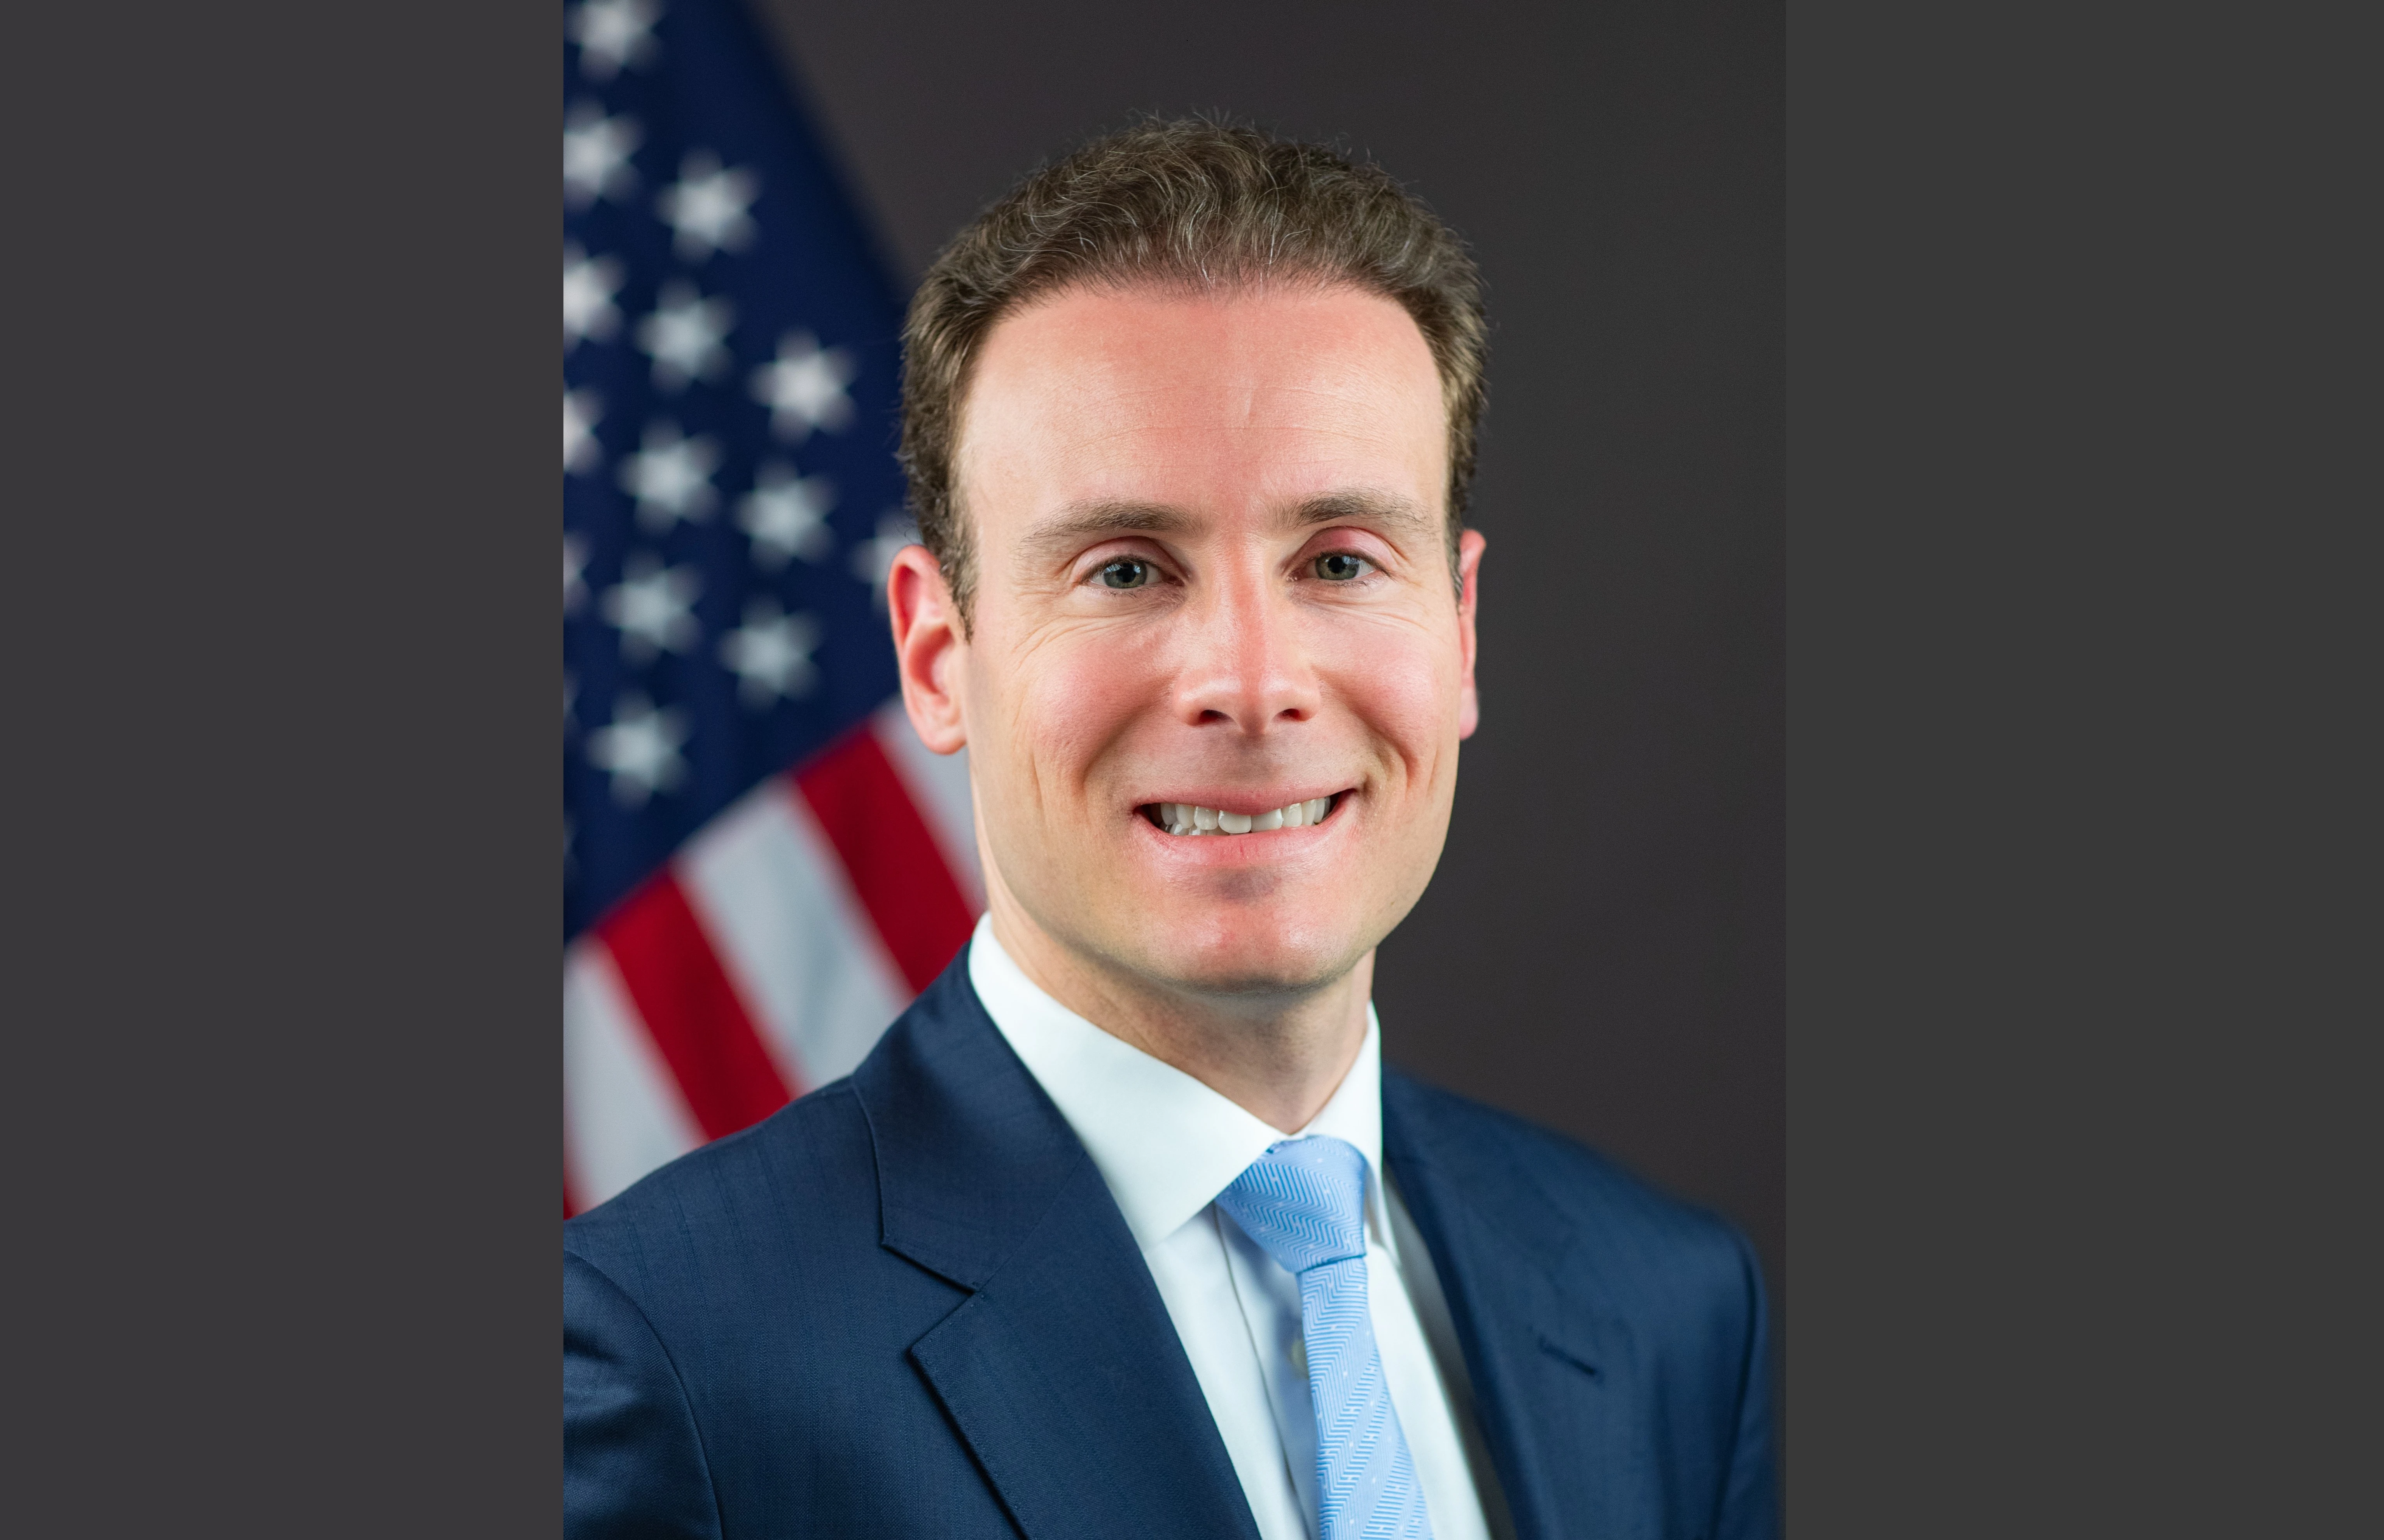
“I join SEC Chairman Atkins in celebrating the end of decades-long jurisdictional 'turf wars' between the CFTC and the SEC that have frustrated innovation and left a void of unrealized financial products in their wake,” said Michael Selig (pictured), chairman at CFTC, in a release.
“Today’s approval order, along with the SEC’s order, reflects a new spirit of harmonization, innovation, and market participant choice, removing unnecessary obstacles to the lawful introduction of novel financial instruments within our markets.”
According to the CFTC’s order, Rothera’s contract meets three parts of the swap definition in the CEA.
First, CFTC said that a company’s adjusted EPS counts as an “excluded commodity”. It is a contingency with financial consequences that no party to the contract can control, and it is not linked to a physical commodity. That makes a binary option on it a swap.
Second, the CFTC noted that the contract’s payout depends on an event associated with a “potential” financial, economic or commercial consequence. The order said corporate KPIs affect suppliers, customers and competitors.
Third, the Commission also cited the provision covering instruments commonly known to derivatives market participants as swaps. It noted that contracts based on similar corporate metrics had previously been listed by designated contract markets, including contracts tied to Tesla vehicle deliveries and Netflix subscriber figures.
Regulatory boundary with the SEC
The order’s central point is why the contract is not a security-based swap, which would fall under the SEC.
CFTC said that even if a KPI is an input into a company’s share price, or acts as a proxy for it, the contract is still based on that metric rather than on the security itself.
The Commission also found the contract does not meet the security-based swap test.
The CFTC pointed to how the product is structured. Rothera’s contract trades as an event contract swap on a DCM. It is not a standardised option listed on a securities exchange under that exchange’s rules on customer accounts, margin, trading halts and market-maker obligations.
That is the model the SEC approved for Cboe on October 13. In its order, the SEC found Cboe’s KPI contracts were securities options, excluding them from the swap definition. It also said similar products on the same KPIs “may be structured in different ways and subject to CFTC jurisdiction”.
The development bypasses decades of jurisdictional turf wars between the two regulators.
“Today’s approval order does not address — and does not foreclose — SEC jurisdiction over KPI contracts based on the same underlying KPIs as those contemplated in the approval order that are structured to fall under the SEC’s jurisdiction. Indeed, our sister agency recognized as much in its own approval order issued earlier this month,” CFTC said in the order.