SEBI delinks expiry-day derivatives settlement from CAS, brings back 30-minute VWAP
16th October, 2026
Aravind Bulusu
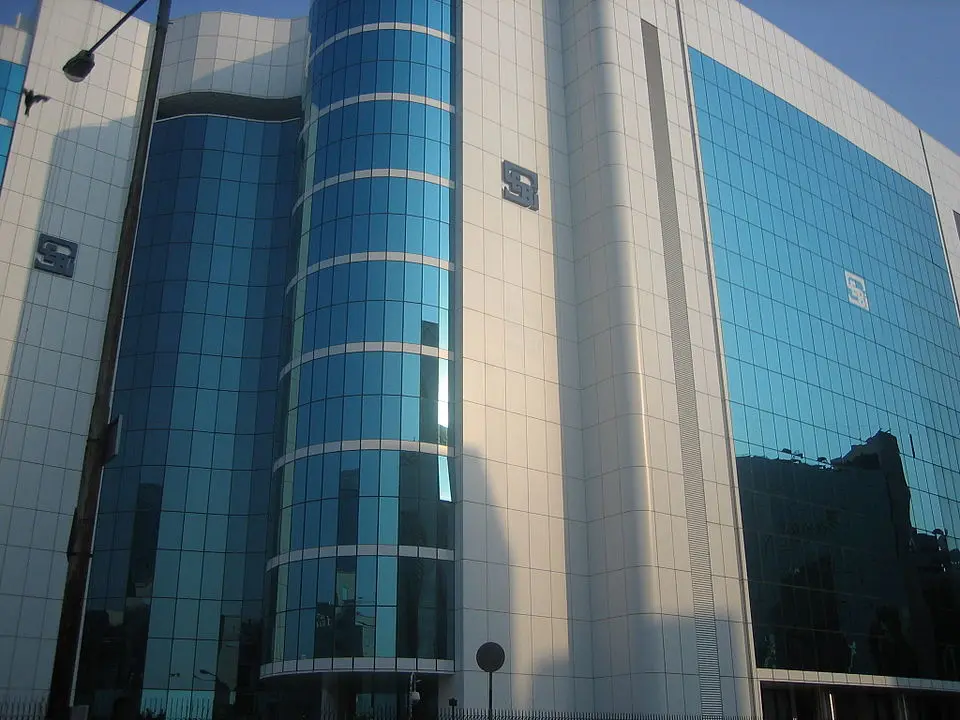
The regulator directed stock exchanges to compute the volume-weighted average prices (VWAP) of underlying indices and securities during the last 30-minutes of the continuous trading session (CTS), for use by clearing corporations in determining the expiry-day derivatives settlement price.
Unlock this article with 1 month’s free and instant access to FOW Intelligence
Go beyond this article with 1 month’s free, no obligation access to FOW Intelligence — bringing you expert insights and analysis backed by our comprehensive volumes database. Everything you need to stay informed and make smarter decisions.
- • Actionable insights across global futures and options markets
- • Exclusive content, including breaking stories and interviews with market leaders
- • Daily newsletter delivering the day’s top stories straight to your inbox
- • Expert analysis to support smarter trading decisions
- • Extensive daily volumes database to monitor activity
- • Trusted by financial professionals for 40+ years

Already have an account?